




Autumn Budget 2026: what it means for your money
How does it affect your savings, investments, and retirement?
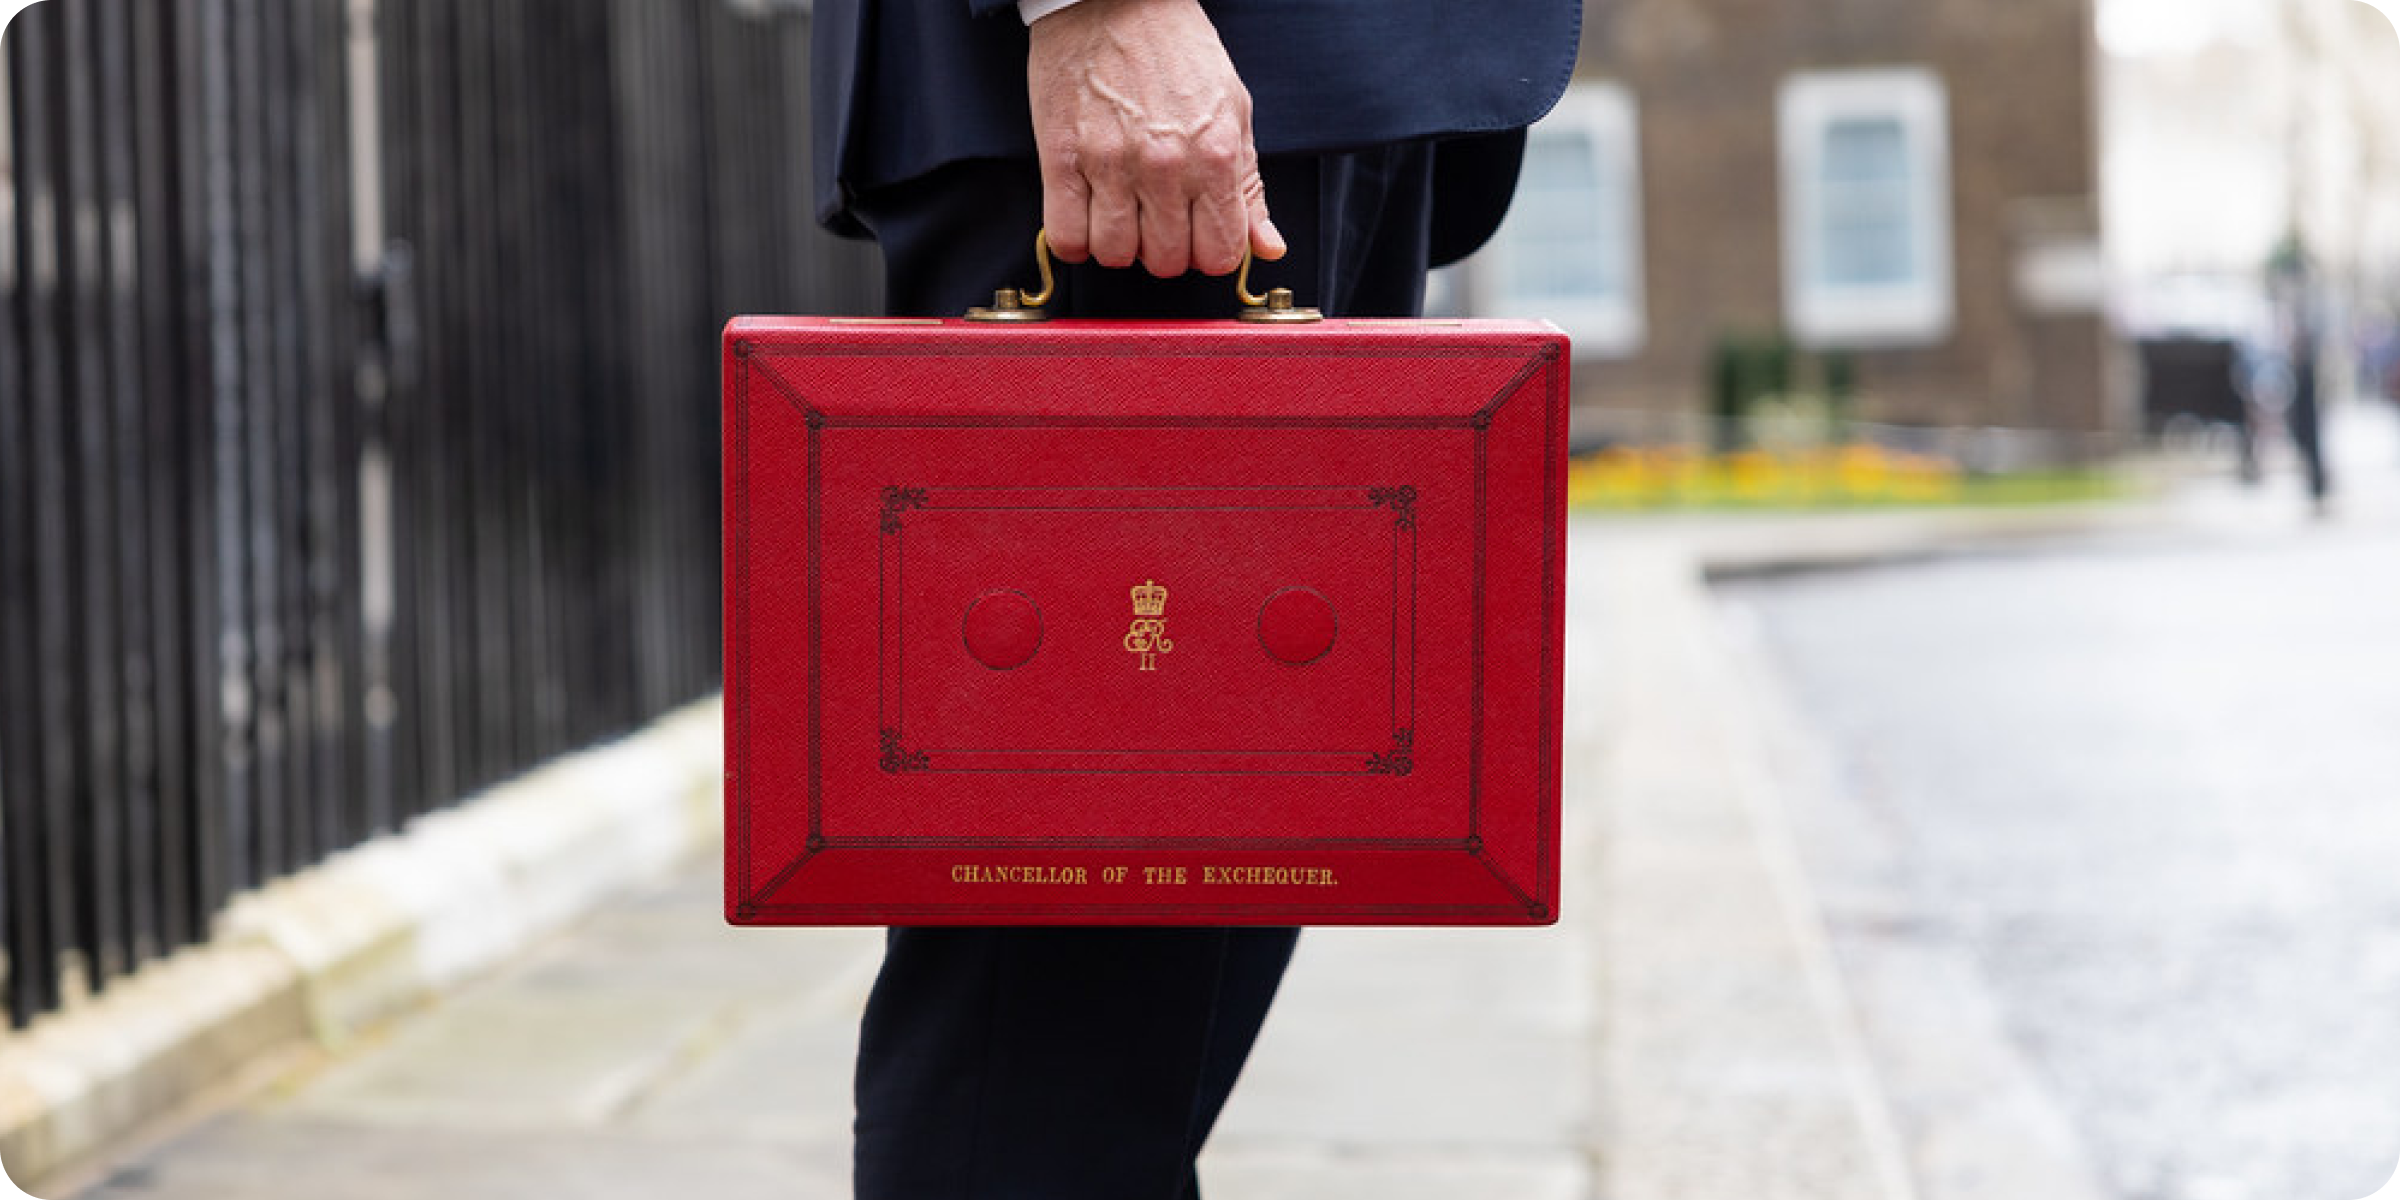
The Chancellor John Healey delivered his first Budget last week and the team at Chip HQ tuned in (so you didn’t have to).
The big headline for our members: the planned cut to the cash ISA allowance has been scrapped.
This means your £20,000 allowance is staying put, but it wasn’t all good news for savers. Here’s our full breakdown.
ISAs took a big U-turn
The Chancellor has scrapped the government’s policy of implementing a £12,000 per year limit on cash ISA contributions for under 65s.
The cut (which would have taken effect from April 2027) was designed to push savers toward investing. Instead, the government will work with the industry on creating a “starter ISA” for first-time investors.
So your £20,000 cash ISA allowance is safe. For now.
What it means for you: The full £20,000 cash allowance isn’t going anywhere, so you can keep making the most of it this year, next year and hopefully beyond.
Savings interest tax
The two percentage point rise in savings interest tax rates from April 2027 remains on course.
Basic rate taxpayers will pay 22%, higher rate 42% and additional rate 47% on savings income outside an ISA. The Personal Savings Allowance stays the same: £1,000 for basic rate and £500 for higher rate taxpayers.
What it means for you: If you hold cash savings outside an ISA, more of your interest earned above your personal savings allowance will be taxed from next April. The case for using your ISA allowance remains strong.
Pensions
A quiet Budget for pensions. Pensioners whose total income is up to the value of the full new state pension won’t pay income tax on it, with the allowance tapering for those just above that level.
The inheritance tax change announced in 2024 still goes ahead. From April 2027, most unused pension pots will count towards your estate.
What it means for you: If you were planning to pass on your pension as part of your estate, it could be worth speaking to a financial adviser before April 2027.
What hasn’t changed
Capital Gains Tax rates are unchanged, despite speculation that they would rise. There’s no rise in tax on dividend income either, which will be a relief for investors. Income tax, National Insurance and VAT rates stay the same. And no changes were announced to pension tax-free cash.
The key takeaways
This Budget had one big surprise: the cash ISA U-turn. With the bigger rise in savings tax earned outside of your Personal Savings Allowance, protecting your cash inside your £20,000 tax-free wrapper will be more valuable than ever.
For investors, it was a quiet one. Capital Gains and dividend tax rates are unchanged, and the government wants more people investing, with the starter ISA its next step. What that looks like? We don’t know yet, but we’ll keep you informed on developments.
While this U-turn was a welcome win for many, it was a reminder that ISA rules can change, so it’s always worth using allowance while you have it.
This article is for informational purposes only. Chip does not provide tax or financial advice. When investing, your capital is at risk. Tax treatment depends on individual circumstances and may be subject to change. If you are unsure how any Budget changes affect you, please speak to an independent financial adviser.