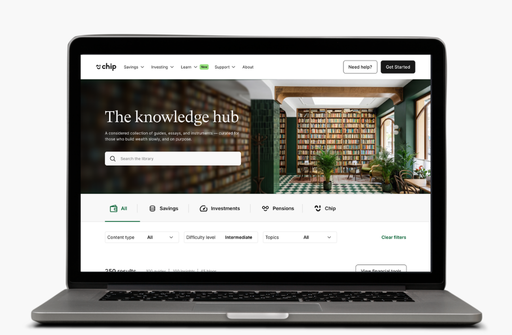
The knowledge hub

A considered collection of guides, essays, and instruments — curated for those who build wealth slowly, and on purpose.

0
results
Filter results
Filter by:
Content type
Difficulty level
Topics
0
results
View financial tools
The art of laddering a wealth building strategy for savvy savers
2 min read
Expert
Savings Strategies & Tips

What is laddering?

Laddering is the practice of dividing your savings across several fixed-term accounts or bonds with varying maturity dates. Instead of locking up all your money in one long-term account or keeping it entirely in easy access savings, you spread it across multiple terms.

This allows you to benefit from better interest rates while ensuring a steady flow of accessible funds.

‍

How does it work?

Imagine you have £10,000 to save. Instead of placing it all in a single account, you could, as an example, split it like this:

  • £2,000 in a one-year fixed-term account
  • £2,000 in a two-year fixed-term account
  • £2,000 in a three-year fixed-term account
  • £2,000 in a four-year fixed-term account
  • £2,000 in a five-year fixed-term account

As each account matures, you would then have the option to access the money or reinvest it in a new five-year account, thus maintaining the ladder.

This way, you will be continuously cycling your savings, while simultaneously benefiting from higher interest rates on long-term accounts.

‍

How to start laddering

Before you start building your ladder, you’ll need to plan ahead:

  • ‍Evaluate your needs: Decide how much you can afford to lock away for longer terms and how much (if any) you’ll need to access in the near future.‍
  • Compare rates: Understand the best fixed-term savings rates.
  • ‍Start small: You don’t need a huge lump sum to get started. Begin with what you have and build your ladder over time.
  • ‍Stay updated: Monitor interest rate trends and economic conditions to make informed decisions when your accounts mature.
  • ‍Understand tax implications: Be mindful of how your interest earnings might impact your tax liabilities, especially if you’re in a higher tax bracket.

‍

Is laddering right for you?

Laddering can be a great option if:

  • You have a lump sum to invest;
  • You want to maximise your savings’ interest without sacrificing liquidity;
  • You’re comfortable managing multiple accounts;
  • You have a stable financial situation and can afford to lock away part of your savings;
  • You need instant access to all your money or are just starting your savings journey, an easy-access savings account may be more appropriate for now.

‍

The bottom line

Laddering is a simple but effective strategy that helps you strike a balance between earning potential and maintaining flexibility.

Whether you’re looking to grow your savings or ensure regular access to funds, this method could be a game-changer for your financial future.

Of course, it’s important to always keep in mind that personal finance is unique to each individual, and what works for one person might not be the best fit for another. Take the time to assess your goals, risk tolerance, and financial needs before implementing laddering in your savings plan.

Please note: Chip only offers savings and investment products, which are listed in its app and website. Chip does not provide financial or tax advice, and this information should not be considered a personal recommendation.

The tax-free lump sum
2 min read
Expert
Accessing your pension

What is the tax–free lump sum?

The tax-free lump sum is a feature of UK private pensions that allows you to withdraw up to 25% of your total pension pot without paying any Income Tax. This option is sometimes referred to as Uncrystallised Fund Pension Lump Sums (UFPLS). 

Unlike the other 75% of your pension, which is taxed as earnings when you withdraw it, this 25% portion can be withdrawn to your bank account in full. You do not need to take it all at once; you can take it in stages, or you can leave it invested if you don't need the cash immediately.

‍

How much of my pension can I take tax-free?

You can normally take 25% of your private pension savings tax-free, but there is a strict lifetime allowance on the total amount of tax-free cash you can draw.

This is called the Lump Sum Allowance (LSA).

  • The current LSA cap is £268,275
  • This represents 25% of a pension pot of £1,073,100. Anything beyond this amount is treated as taxable income. 

Some older pensions with ‘protected’ rights allow for a higher tax-free amount than 25%. Check your policy documents to see if this applies to you.

‍

Can I take my pension as a lump sum? 

You could technically take your entire pension at once, as a lump sum. However, if you cash in the whole pot, usually:

  • 25% is tax-free
  • The remaining 75% is taxed as income

It’s worth noting if you do decide to do this, the 75% taxable portion is added to your income that year. If you withdraw a large pot, this could easily push you into the Higher (40%) or Additional (45%) rate tax bracket; meaning you’d be taxed a huge chunk of your pension.

Note: There are several exceptions to the standard 25% tax‑free rule. These include serious ill‑health (where the whole pot may be tax‑free), small pots under £10,000, older pensions with protected tax‑free cash, defined benefit schemes with different calculation rules, and certain death‑benefit situations.

‍

Do I have to declare my pension lump sum? 

No, you do not need to declare the tax-free portion of your pension as it is not taxable income. However, if you take any cash beyond your tax-free Lump Sum Allowance, your provider will deduct tax before paying you. 

Providers typically have to apply an ‘emergency tax code’ to your first withdrawal, which may result in them over-taxing you initially. You would then have to reclaim this overpaid tax from HMRC.

‍

Lump sum: pay off your mortgage or invest? 

A common question for pension savers is whether to use their tax-free lump sum to pay off some, or all of their mortgage or to leave the money invested. Both options have advantages but the right choice depends on their personal circumstances.

Paying of your mortgage:

  • By paying off debt, you effectively earn a ‘guaranteed return’ equal to your mortgage interest rate. If your mortgage rate is 5%, paying it off saves you that 5% interest cost. 
  • Being mortgage-free would likely also reduce your monthly outgoings, meaning you need less income from your pension to cover your expenses.. 

Staying invested:

  • If your investments grow faster than the interest you’re paying on your mortgage, for example, it’s returning 7-8% to your 4% mortgage interest, you could come out ahead.
  • Property is an ‘illiquid’ investment — once your money is locked into property, it’s more difficult to access quickly. Keeping the funds in a savings or investment account usually leaves them more readily accessible.

‍

Pension drawdown

When thinking about what to do with the remaining taxable 75% of your pension pot, you have a couple of options. The first option covered in the next guide is the most popular; flexible drawdown. 

Flexible drawdown allows you to pay yourself an income of your choosing from your invested pension pot. It gives you the freedom to take as much or as little as you like, but it also means you’re responsible for managing your withdrawals and ensuring your money lasts throughout retirement.

‍

How much do I need to retire?
2 min read
Intermediate
Building your pension

What is a good pension pot? 

A ‘good’ pension pot is one that generates enough income for you to cover your expenses during retirement. As life expectancy increases, so does the necessity for a larger pension pot.

To work this out, you need to think about annual expenses, not just a total lump sum. We’ll use a defined contribution pension pot as an example, as defined benefit schemes offer a largely guaranteed income.

  • The 4% rule: The 4% rule: A helpful, if not failsafe, rule of thumb for calculating sustainable income. Withdrawing 4% of your total pot in year one, then adjusting for inflation each year, has historically given a strong chance of your money lasting 30 years — though some advisers recommend a more conservative rate of 3–3.5%.
  • An example calculation: To get an income of £20,000 from your private savings (on top of the State Pension) you’d need a pot of roughly £500,000. 

‍

How much should I have in my pension? 

While everyone’s journey to retirement is different, there are some rough age-based benchmarks to help check if you’re on the right track.

  • At 30 you should aim to have saved your current annual salary, once. For example, if you earn £30,000, you should have £30,000 in pension savings.
  • At 40 you should aim to have saved three times your annual salary. For example, if you earn £30,000, you should have £90,000 in pension savings.
  • At 50 you should aim to have saved six times your annual salary. For example, if you earn £30,000, you should have £180,000 in pension savings.

These are great scenarios but if you are behind where you need to be, don’t panic — saving for retirement is a marathon, not a sprint. You can catch up by increasing your contributions later in your career.

‍

Retirement Living Standards (PLSA) 

The Pensions and Lifetime Savings Association (PLSA) publishes the Retirement Living Standards.

These act as a practical guide to help you understand how much income you might need to achieve different standards of living in retirement (calculated after income tax).

These figures are updated for the 2025/26 Tax Year and assume you will be mortgage-free by the time you retire.

The Minimum Lifestyle
  • Cost: £13,900 (one-person) | £22,500 (two-person)
  • What it covers: All your basic, essential needs with a little left over for fun. It includes a UK holiday (self-catering or half-board), one meal out per month, and affordable weekly leisure activities, but no car.
  • Amount needed: For a two-person household, two full State Pensions combined usually cover this standard. A one-person household will generally need a small private pension pot to top up the State Pension and bridge the gap.
The Moderate Lifestyle
  • Cost: £32,700 (one-person) | £45,400 (two-person)
  • What it covers: Increased financial security and more flexibility. You can run a small car (replaced every 7 years), take an annual 2-week overseas holiday alongside a UK long weekend break, and enjoy eating out or ordering takeaways a few times a month.
  • Amount needed: A one-person household would typically need the full State Pension supplemented by a private pension pot of roughly £335,000 to £505,000.
The Comfortable Lifestyle
  • Cost: £45,400 (one-person) | £62,700 (two-person)
  • What it covers: More financial freedom, spontaneity, and some luxuries. You can replace a small car every 5 years, enjoy regular theatre trips or day outings, take a 2-week foreign holiday (up to 4-star), and enjoy up to three UK long weekend breaks every year.
  • Amount needed: A one-person household would typically need the full State Pension supplemented by a private pension pot of roughly £560,000 to £845,000.

‍

What is my retirement age? 

There are two key ages to know when it comes to accessing your pension pots. You can of course choose to stop working earlier, but only if you have enough savings to fund your lifestyle without drawing on these pots.

Outside this scenario, these are:

  • State Pension Age: This is when the government starts paying you. Currently, it is 66, rising to 67 between 2026 and 2028. Read our full guide on the State Pension.
  • Normal Minimum Pension Age (NMPA): This is the earliest you can usually access your private or workplace pension. Currently, it is 55, but it will rise to 57 on 6 April 2028.‍

Note: If you were a member of a pension scheme before 3 November 2021, you may have a 'protected pension age' — meaning you could still access that pension from age 55, even after the 2028 change. This applies at scheme level, so it's worth checking each pension you hold individually, as the protection may not apply to all of them. 

Read our full guide on retirement ages.

‍

Pension contributions

Once you’ve worked out how much you need to retire, the next step is working out how to get there.

Hitting a £500,000 target might sound impossible if you just look at your salary, but you don’t have to do it alone.

Between tax relief and employer contributions, the amount landing in your pot can be significantly more than what you actually pay from your salary or savings.

In our next guide, we break down exactly how these contributions work and the ‘golden rule’ for how much you should be contributing based on your age.

‍

Fractional shares explained
2 min read
Beginner
Investing trends

What are fractional shares?

A fractional share is exactly what it sounds like — a portion of a full share of stock or an ETF.

Instead of needing the full amount to purchase a whole share (which can sometimes cost hundreds or even thousands of pounds), fractional shares allow you to invest an amount that fits your budget, whether that’s £10, £100, or more.

  • For example, if a single share of a company costs £200 and you invest £20, you would own 0.1 of a share.

Fractional investing is made possible by modern brokerage platforms, and it’s especially popular among new investors or those looking to spread small amounts across many companies or funds.

‍

Understanding types of fractional shares

Not all fractional shares are created equally. Here's a breakdown of the main types you might come across:

  • Voluntary fractional shares: These are intentionally created when investors choose to buy a specific monetary value rather than a number of whole shares. Most common in retail investing today.
  • Involuntary fractional shares: These occur due to events like stock splits, dividend reinvestment plans (DRIPs), or mergers and acquisitions.‍
  • Fractional shares via ETFs and funds: Some exchange-traded funds (ETFs) and index funds inherently involve fractional share ownership behind the scenes, allowing for diversified exposure even with small investments.

Understanding the source of your fractional shares can influence how they’re treated in terms of ownership, voting rights, and dividend payouts.

‍

How does trading fractional shares work?

When you trade fractional shares, you're typically placing an order based on a cash amount, not the number of shares. 

Your investment platform calculates how much of a share that amount will buy based on the current market price.

A few important things to note for UK investors:

  • Execution timing: Some providers batch fractional share orders and execute them at specific times during the day, rather than instantly.
  • Ownership model: In most cases, you don’t directly own the share certificate. Instead, your platform holds it on your behalf, often via a nominee account.
  • Fees and spreads: Be aware of how fees and bid-ask spreads may affect your investment, especially with smaller sums.

‍

Example of fractional shares

Let’s say you’re interested in investing in a company or ETF and shares are trading at £500 each. Rather than saving up to buy a whole share, you decide to invest £50. You now own 0.10 of a share.

If the share price increases by 10% to £550, your investment would be worth £55, a £5 gain, reflecting the same percentage growth.

This ability to invest smaller amounts can be particularly helpful when building a diversified portfolio across different sectors and asset types.

‍

Fractional shares and dividends

If the fractional shares you own pay a dividend, you’re typically entitled to a proportional dividend.

For example, if a company pays a £2 dividend per share and you own 0.5 of a share, you would receive £1 in dividends. However, how and when these dividends are distributed can vary by provider. 

‍

Pros & cons of fractional shares

Fractional shares advantages:
  • Lower barrier to entry: Start investing with small amounts of money.
  • Diversification: Spread your funds across more assets, reducing risk.‍
  • Accessibility: Invest in high-priced shares that would otherwise be out of reach.
Fractional shares disadvantages:
  • Limited voting rights: Some platforms do not extend shareholder voting rights to fractional holders.
  • Trading limitations: Selling may be restricted or delayed depending on the provider, and you may not receive the price you expect.
  • Platform dependency: You typically cannot transfer fractional shares between platforms or brokers.

‍

Are fractional shares safe and regulated?

Yes, when offered by FCA-regulated platforms, fractional shares are considered a safe and legitimate way to invest.

However, investors should understand that the underlying risks of market investing remain the same, your investment value can go up or down.

As with any investment, due diligence is key. Make sure to check whether your provider is covered under the Financial Services Compensation Scheme (FSCS) and understand how your assets are held.

‍

Fractional shares summary

Fractional shares have opened the door for more people to begin investing, regardless of how much capital they have to start with. 

By making it possible to own a piece of high-priced stocks or ETFs and diversify with less money, they represent a meaningful shift in how modern portfolios are built, especially for new or budget-conscious investors.

That said, it's important to understand the mechanics, limitations, and regulatory environment that surround fractional investing.

While they offer flexibility, they're not a guarantee of returns and carry the same risks as full-share investing.

In recent years, the rise of financial technology, or fintech, has dramatically reshaped how people manage, save, and invest their money.

From user-friendly mobile apps to AI-driven investment platforms, technology is removing many of the traditional barriers to entry in the world of finance.

In the next guide, we’ll explore how fintech is reshaping the future of investing, and what it means for everyday investors.

‍

Direct investment into individual bonds is not available via the Chip platform. Chip offers investment funds that invest in different assets as a collective investment.

What is a bull market?
2 min read
Beginner
Investing basics

A bull market is a period when a broad market index, like the S&P 500, rises by 20% or more from its recent lows. This upward trend is fuelled by widespread investor confidence and optimism, which drives a sustained period of increasing prices.

During a bull market, investors use various strategies to try and profit from the rising values. A bull market is the direct opposite to a bear market, which is a market drop of 20% or more. 

‍

When are we in a bull market?

Similar to bear markets, bull markets can only be identified retrospectively, once a major index has risen 20% or more from a recent low. 

Certain economic signals and market conditions can create the environment for a bull market:

  • Strong economic growth: When the economy is expanding, it's a powerful driver for the stock market. Key signs include low unemployment, rising GDP, and healthy wage growth, which all contribute to higher consumer spending.
  • Rising corporate profits: A bull market is built on the success of businesses. When companies consistently report strong earnings and positive future outlooks, it boosts investor confidence and drives their stock prices higher. 
  • High investor confidence: When investors feel positive about the future of the economy and corporate earnings, they are more willing to buy stocks, creating upward momentum.
  • Supportive monetary policy: When central banks, like the Bank of England, keep interest rates low or stable, it makes it cheaper for companies to borrow and invest. This stimulates the economy and often makes stocks a more attractive investment compared to lower-yielding bonds or savings accounts.

‍

How long do bull markets last?

Although no two bull markets are the same, historical data shows bull periods far outlast bear periods on average. For example, the average duration of the seven bull markets between 1969 and 2024 was six years and nine months. In contrast, the average duration of the six bear markets in the same period, was one year and three months.1

The contrast in this data is central to the principle that over time, markets have trended upwards, more than they have downwards. The crucial takeaway is that staying invested is important for maximising potential returns, as even if you miss the bad days, you could also be missing out on great runs too. 

‍

What does bullish mean?

A bullish investor expects an upward trajectory in prices (the direct opposite of being bearish). Confidence is typically based on positive signs such as:

  • Strong company earnings reports.
  • Positive economic news e.g. declining unemployment.
  • Innovative new products or services.
  • Favourable industry trends.

A bull’s primary goal is to profit from these rising prices. The most common strategy is simply buying an asset and holding it, also known as ‘going long’. This principle can be applied by any investor hoping to generate returns in the market.

More active investors might take more risk:

  • Buying call options: essentially reserving the right to buy a stock at a set price, which becomes profitable if prices rise beyond the call level. 
  • Growth stocks: speculating on companies in high-growth sectors, which have historically yielded greater returns than the rest of the market. 

‍

How to approach a bull market?

It’s important to approach bull markets with the same disciplined approach you’d apply to any investing scenario. The ultimate goal is to not miss out on the upward trend, whilst not being driven by emotion which can lead to mistakes. For example:

  • Staying invested but avoiding FOMO: it can be tempting to chase ‘hot stocks’ in high-growth areas in order to pursue the biggest gains, but it’s important to balance opportunity with your risk level. Don’t jump in with more money than you’re comfortable investing, and stick to your long-term plan. 
  • Review and rebalance: bull runs can cause your portfolio to drift from its set targets. Better performing assets will grow to become a larger percentage of your holdings, causing an unintentional shift in risk. Consider rebalancing to your original allocations, by moving assets from overperforming to underperforming assets to lock in some gains and stay diversified.
  • Regular investing: by sticking to your usual regular investment plan, you won’t get drawn into trying to time the market. A steady approach ensures you're exposed to differing purchase prices, rather than going all in at a potential market high.

Bull markets don’t last forever. Whilst they can present solid opportunities for gains, and staying invested is important, it’s equally important to not get carried away and invest more than you’re comfortable with. Stick to your investing plan and avoid getting too caught up in the latest trend, as you may become overweight in a particular theme or market, without even realising. 

Read our full guide of economic indicators investors should consider.

‘I had a superpower’ Investors pile into brain implants

2 min read

Jasaun Knight remembers the first time he operated a PC using only his brain.“The experience of controlling a computer with my thoughts, moving a cursor around the screen and playing games, was mind-blowing,” said the 35-year-old American. “It was like telekinesis.

I felt I had a superpower.”Knight is one of fewer than 200 people worldwide who have been implanted with a brain-computer interface (BCI) — a device that detects neural activity and translates it into digital commands.

BCIs have the potential to restore speech and movement to people who have lost them through injury or disease. If the technology becomes safe and affordable, it could turn computers and artificial limbs into more direct extensions of the human body, reshaping the relationship between people and machines.

Companies developing BCIs have already raised more than $1bn in 2026, according to PitchBook data, compared with $1.56bn in the previous four years combined.

Neuralink, founded by Elon Musk a decade ago, is the best-funded, having raised more than $1.3bn in seven rounds. But dozens of competitors are pulling in substantial investments as they pursue a range of approaches to connecting computers to the nervous system.

“The field is advancing rapidly as investors move into neurotechnology, though it has already been well characterised and validated in academia,” said Michael Mager, chief executive of New York start-up Precision Neuroscience, which made Knight’s implant. “We in industry are now taking this transformative technology and making it into products that will have a broad impact.”

The most ambitious companies are developing “invasive” devices inserted through a surgical incision in the skull. Some, like Neuralink, have electrodes that penetrate the brain and are designed for long-term use. Others, including Precision Neuroscience, are developing thin, flexible BCIs that sit on the surface of the brain without piercing it.

Knight received his device during surgery for brain cancer as part of a clinical trial that lasted a few days.

Source: US National Library of Medicine.

‍

“I didn’t feel anything physically in my head,” he said. “Once you get the hang of it, your thoughts control what’s happening on the computer screen with no effort at all. ”Another area of research involves non-invasive systems placed on the scalp, which avoid the need for surgery altogether.

However, although they can be useful for diagnosis and research, the brain signals they receive are weakened by passing through the skull, and the devices are not yet sensitive enough to convert thoughts into dependable computer instructions. “All the hype and the funding is going into implantable BCIs,” said Damien Coyle, director of Bath University’s Institute for the Augmented Human.

“With non-invasive techniques the spatial resolution of signals is not so good, but they have a lot of scope for development over the next few years, for example to modulate brain activity. ”US companies including Synchron, Blackrock Neurotech, Axoft and Merge Labs benefit from deep American venture capital markets and a Food and Drug Administration that executives regard as more responsive than regulators in Europe.
‍

Axoft’s Fleuron BCI neural implant

‍

But a cluster of innovative BCI companies is emerging in Europe, among them CorTec in Germany, Onward Medical in the Netherlands, Spain’s InBrain, and Neurosoft and Ability Neurotech in Switzerland.

“The advantages of a European location lie in our deep engineering and precision manufacturing heritage as well as our talent in neuroscience,” said Frank Desiere, CorTec chief executive.

However, he added that Europe “has a real gap in late-stage funding and scale-up capital, as well as a fragmented reimbursement landscape”, and that the continent lacked a regulator “guiding and consulting manufacturers like in the US”.

The company has chosen US sites — the University of Washington and Mayo Clinic — for the first clinical trials of its BCIs.

Meanwhile, the industry is also growing rapidly in China following Beijing’s designation of BCIs last year as a nationally strategic sector, with a roadmap to create two to three “world-class” companies by 2030.

Several provinces have launched investment funds and industrial zones, backed start-ups and supported hospitals running clinical trials.

Private investors have followed suit. In the first half of 2026, VCs poured Rmb7bn ($1bn) into the broader neurotech sector across 60 investments, according to ITJuzi data.

Roughly a dozen Chinese companies are working on invasive BCI devices, according to a tally by the FT, with a much larger number developing non-invasive applications.

One leader in the field is NeuroXess, founded in Shanghai in 2021, which is developing flexible implants to treat severe neurological disorders.

Analysts say China has a strong advantage with its large patient population for clinical trials and regulatory support for accelerating the technology’s development.

Most BCIs work in one direction, reading signals from the brain and turning them into electronic commands. But some companies are developing systems that can also send signals back, creating a two-way exchange between brain and machine known as closed-loop stimulation.

CorTec is among them. “It’s like having a dialogue with the brain, adapting our therapy to the individual signals of the patient,” said Desiere. “In strokes we target the motor cortex, reading and stimulating the cells there so that they fire together. Neurons that fire together wire together.

”One of neurotech’s biggest opportunities may come when BCIs converge with another rapidly advancing field: prosthetics. Artificial limbs have been around since ancient times but developments in sensors, materials, batteries, motors and software are making them lighter, more capable and easier to control.

Bristol-based Open Bionics makes arms fitted with sensors that detect movement in a user’s remaining muscles and transmit the signals to the prosthetic hand.
‍

Open Bionics CEO Joel Gibbard with the company’s products

While the investment climate has fluctuated during the company’s 12-year existence, its revenues have grown at a compound annual rate of 60 per cent since 2018.Yet even the most advanced artificial hands lack much of the dexterity and sensation of the biological original.

The technical capability to build a hand that replicates many natural movements already exists, according to Joel Gibbard, Open Bionics co-founder and chief executive. But the systems used to control them remain “very, very rudimentary” — a problem BCIs have the potential to resolve.

Researchers hope a direct link to the brain could eventually provide the missing interface — and, if signals flowed both ways, restore a sense of touch.Meanwhile, Open Bionics is embracing the superhero associations of its technology.

Its Hero Arm offers children designs based on characters from franchises including Black Panther and Metal Gear through licensing agreements with companies including Disney.“There are technical limitations for today, but what people think about for the future is inspired by movies and science fiction,” said Gibbard.

‍

Source: Precision Neuroscience

Back in New York, Knight, a former insurance agent who is now training as a software engineer, is considering a new career in neurotech — helping to develop the kind of systems he helped test.“After my experience,” he said, “I’d probably be a perfect candidate.”
What is the UK unemployment rate and why do investors care?
2 min read
Intermediate
Economic context

Every month, the Office for National Statistics (ONS) releases the latest figures on the UK labour market from its Labour Force Survey (LFS). While this data is obviously important news for job seekers and politicians, it is also one of the most closely watched days in the calendar for investors. 

The Unemployment Rate represents the percentage of the labour force that is without a job but is actively seeking work. It’s important to note that this figure doesn’t include everyone who isn’t working. Students, retirees, and those not looking for a job are classified as ‘economically inactive’. 

When investors are interpreting unemployment figures, they’re typically looking for three things:

  1. The headline rate: Is this figure going up and down? 
  2. Wage growth: Are pay packets getting bigger?
  3. Vacancies: Are companies trying to hire?

‍

Why do investors care?

For investors, employment data is a key economic health indicator and can be a key catalyst for other key indicators. It can have a direct effect on interest rates, consumer spending and inflation. 

‍

The link to interest rates

This is the biggest reason the markets care about jobs data. Unemployment is a key data point for the Bank of England Monetary Policy Committee when determining their base rate of interest, which determines the cost of borrowing for other banks. 

If unemployment is low: businesses are in greater competition over staff, pushing wages higher. When wages increase, so does consumer spending, and inflation can follow suit. The Bank of England may raise interest rates to stop the economy from ‘overheating’. Higher rates are tougher on borrowers, and cause markets to dip as debt becomes more expensive. 

If unemployment rises: this suggests a potential slow down in the economy, and the Bank of England may cut interest rates to try and stimulate growth. Lower rates are often welcomed by markets and investors, as they make borrowing cheaper and encourage spending.

‍

The link to corporate profits

The UK economy is heavily driven by consumer spending, and this has strong links to employment.

When jobs are safe (low unemployment): People buy cars, book holidays and subscribe to services. This pushes profits up for consumer goods and services companies like airlines, high-street shops and restaurants.

When jobs are at risk (high unemployment): Consumers tighten their fists and generally stick more to essential spending. In this environment, consumer essentials suppliers like supermarkets and utilities tend to show more resilience, whilst higher end discretionary spending like luxury goods and leisure suffer.    

‍

The ‘good news is bad news’ conundrum

Drawing a clear link between job growth and a robust economy can be tricky, and the stock market's reaction to positive employment data is not always consistent. 

This often happens due to inflation fears. If the job market is doing ‘too well’, investors’ inflation fears deepen, and predictions of Bank of England rate increases can dampen market spirits. Markets prefer a stable number that shows a strong economy, without being so strong inflation fears creep in. 

‍

Read our full guide on economic indicators investors should watch out for.

‍

Safeguarded benefits and your pension
2 min read
Beginner
Pension basics

What is a safeguarded benefit?

A safeguarded benefit is a promise about your pension. It might be a guaranteed income for life, or a guaranteed rate for turning your savings into an income.

Most modern pensions are simply a pot of money with no promise attached. These are called defined contribution pensions, and they’re the kind Chip is built for. Safeguarded benefits are more common in older pensions, often set up in the 1980s and 1990s.

‍

The main types to look out for: 

  • Defined benefit (or final salary) pensions. These pay you a set income for life, based on your salary and how long you worked there. The income is guaranteed, so it doesn’t rise and fall with the stock market.
  • Guaranteed annuity rate (GAR). A promise that you can swap your pot for a guaranteed income at a set rate. Older rates are often far higher than the rates available today, so this can be very valuable.
  • Guaranteed (or protected) pension age. The right to take your pension earlier than the normal age, which is currently 55 and rising to 57 in April 2028. Transferring could mean losing this.
  • Guaranteed minimum pension (GMP). A minimum amount your scheme must pay you. You may have this if you were “contracted out” of part of the State Pension before April 1997.
  • Other guarantees. Some pensions also include guaranteed growth or bonus rates, or let you take more than the usual 25% as tax-free cash.

‍

Why this matters

Guarantees like these are hard to find anywhere else, and you usually can’t replace them once they’re gone. Giving one up could leave you worse off in retirement. That’s why there are extra rules in place to protect you.

‍

Can Chip accept a pension with safeguarded benefits?

No. Chip’s pension is built for old defined contribution pensions, which are a simple pot of money. We can’t accept a transfer that includes safeguarded benefits or guarantees, regardless of value. If your pension has a guarantee, the safest thing is usually to leave it where it is.

‍

If you’re thinking about moving it

If you still want to move a pension that has guarantees you should consider whether to speak to a regulated financial adviser first. They can look at your situation and tell you whether it’s the right move for you.

In some cases the law requires this. If your safeguarded benefits are worth more than £30,000, you must take regulated advice before you can transfer, and the provider you’re leaving has to check that you’ve done so.

‍

Before you transfer, check for:

  • a guaranteed income, or a guaranteed annuity rate
  • the right to take your pension before age 55
  • a guaranteed minimum pension, if you were contracted out
  • exit fees or penalties for leaving
  • valuable extras, such as life cover or extra tax-free cash

Your current provider can tell you. You can also check your most recent statement or your scheme booklet.

‍

Not sure what you have?

If you’re not sure what type of pension you have, or whether it comes with any guarantees, ask your current provider. They can tell you for free.

‍

Where to get free help

For free, impartial guidance, you can contact MoneyHelper, which is backed by the government.

To find a regulated financial adviser, you can use the directory on MoneyHelper, or check the Financial Conduct Authority register to know whether a firm or advisor is authorised by the FCA.

If you’re 50 or over, you can also book a free pension appointment with Pension Wise.

The state pension
2 min read
Beginner
Pension basics

What is the State Pension? 

The State Pension is a regular payment you receive from the government during retirement, funded by your National Insurance contributions during your working years. 

There are currently two systems in operation, depending on your age:

  • The “new” State Pension: For men born on or after 6 April 1951 and women born on or after 6 April 1953.
  • The “basic” State Pension: For anyone born before those dates.

‍

What is the State Pension age? 

The State Pension age is the earliest age you can start receiving your payments. This is set by the government and is subject to change.

  • Currently the State Pension age is 66 for both men and women.
  • Future changes have been legislated for a rise to 67 between 2026 and 2028.

‍

How much is the State Pension? 

The amount you’ll receive is based on which system you fall under and your National Insurance. These rates apply to the 2025/2026 tax year. 

  • The full rate for the new State Pension is £241.30 a week (approx. £12,547 a year)
  • The full rate for the basic State Pension is £184.90 a week (approx. £9,615 a year)
For couples 

A common question is whether a joint amount is paid out to couples. The State Pension is based on your individual National Insurance record, meaning you and your partner will claim separate amounts. If you both qualified for the full State Pension, you’d receive an income of approximately £25,095.

For a widow 

If your spouse or civil partner passes away, you may be able to inherit some of their State Pension, but the rules around this are complex. 

  • Under the old system (reached pension age before 2016) you can often inherit a significant portion of your partner's ‘Additional State Pension’ (SERPS).
  • Under the new system (reached pension on or after 6 April 2016) it is much harder to inherit. Typically, you can’t inherit their main pension, but you may inherit a ‘protected payment’ if they built up a very large pot under the old rules. 

‍

How much State Pension will I get? 

The amount you receive is not a fixed salary, it is a payment calculated from your ‘qualifying years’ of National Insurance (NI) contributions.

A qualifying year is one in which you were working and made NI contributions, received NI credits (e.g. you were ill, unemployed or a carer), or made voluntary NI contributions. 

  • To qualify for the full amount you generally need 35 qualifying years.
  • To qualify for any amount you need at least 10 qualifying years.
  • To qualify for a proportional amount you’ll need between 10 and 35 qualifying years (e.g. 18 years would qualify you for half the full amount). 

‍

How do I check my State Pension forecast?

If you want to check how much State Pension you might qualify for, you can do this online.

Check your State Pension forecast using the free tool on the government website.

‍

When do I get my State Pension?  

You can claim your State Pension up to four months before you reach your qualifying age. This is then paid directly into your bank account every four weeks . 

The State Pension is taxable income, however, this is not deducted from the payment directly; it makes up part of your Personal Allowance.

Any due tax is usually taken from your other income sources like a private pension or salary. 

What is the full State Pension?

The ‘full State Pension’ refers to the maximum standard rate (£241.30 per week for the new State Pension).

However, it is possible to receive more than this if you have deferred (delayed) taking your pension, or if you have ‘Protected Rights’ from the old system. 

‘Protected Rights’ refers to a protection of claimants of the old ‘additional’ State Pension, who were entitled to receive more than the new full State Pension. 

‍

What is Pension Credit? 

Pension Credit is a separate, tax-free benefit for people over State Pension age who are on a low income.

It is distinct from the State Pension because it is means-tested; based on your income and savings, not your National Insurance record. 

It is often called a 'gateway benefit' because claiming it can unlock other support, such as free TV licences (for over-75s) and Council Tax reductions.

The Winter Fuel Payment is now available to pensioners with an income up to £35,000, but Pension Credit remains the most reliable route to ensure you receive it if you are on a low income. 

How much is Pension Credit a week? 

For the 2026/27 tax year, Pension Credit tops up your weekly income to a guaranteed minimum level:

  • For single people this is £238.00 per week.
  • For couples tops up joint income to £363.25  per week.

If you have a disability or caring responsibilities, you may be entitled to extra amounts on top of this.

Who is eligible for Pension Credit? 

You must live in England, Scotland, or Wales and have reached State Pension age.

  • Income rule: Your weekly income generally needs to be below the thresholds listed above.
  • Savings rule: If you have savings over £10,000, your entitlement is reduced. For every £500 you have over £10,000, it counts as £1 of weekly income. 
How to apply for Pension Credit? 

You can apply online via the GOV.UK website, by post, or by phone. You will need your National Insurance number, details of your income/savings, and your bank account information. 

  • Pension Credit Claim line: 0800 99 1234

‍

Workplace pensions

While the State Pension provides a guaranteed safety net, £12,500  a year is likely far too little for a comfortable retirement.

Creating the lifestyle you dream of after you stop working may require a second stream of income. 

For most people, this comes from their workplace pension, which is arguably the most powerful savings tool available to UK employees. When you pay in, your employer has to pay in too.

Read our next guide and get a better understanding of workplace pensions.

‍

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.