



We can help.

Get the Chip App
Scan the QR code to download the app.

or get a download link via email.
Chip Everyday Savings Account




A savings account for your everyday
Our simple savings account for whatever your saving for. With total freedom on your deposits and withdrawals.
Here’s how it works

You’re in control
Save your way with easy access and unlimited withdrawals. Earn interest with the total freedom of having your money there when you need it.
Built for flexibility
Take out what you need, when you need it, with no notice or charges. With you next working day.
Why settle for 0%?
The Everyday Savings Account is perfect for earning interest on money sat idle in your current account.
Held with UK banks
Deposits sit across a panel of UK licensed banks. Eligible deposits are FSCS protected up to £120,000 per person, per bank.
Why open an Everyday Saver with Chip?

Chip is designed to grow your wealth
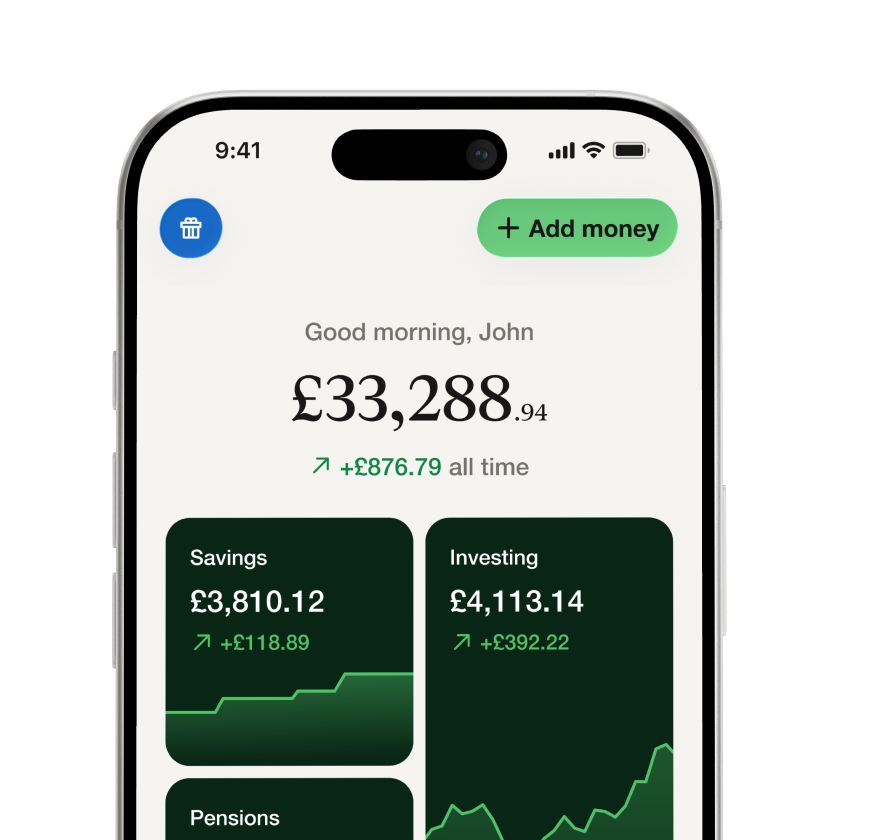

Earn rewards for building your balance


We’re here for you, seven days a week
What is an everyday savings account?
An everyday savings account pays interest on your savings while letting you take your money out when you want it.
There's no notice period and no limit on withdrawals, which makes it suited to money you might need at short notice rather than money you're happy to lock away for a fixed term.

Access without conditions
Deposit and withdraw as often as you like, with no fixed term, no lock-in and no charge for taking money out. With the Everyday Savings Account, withdrawals reach your bank the next working day.

Protected up to £120,000
Eligible deposits are protected under the Financial Services Compensation Scheme up to £120,000 per person, per bank.²
2Your deposits are held in a bare trust account and placed across a panel of UK licensed banks: HSBC Bank Plc, Lloyds, QNB. These are subject to change. The £120,000 limit applies to your total balance with each bank, including any accounts you hold with them directly.
How to open your account
We've made it easy to get started with all our savings accounts. Open yours in minutes.
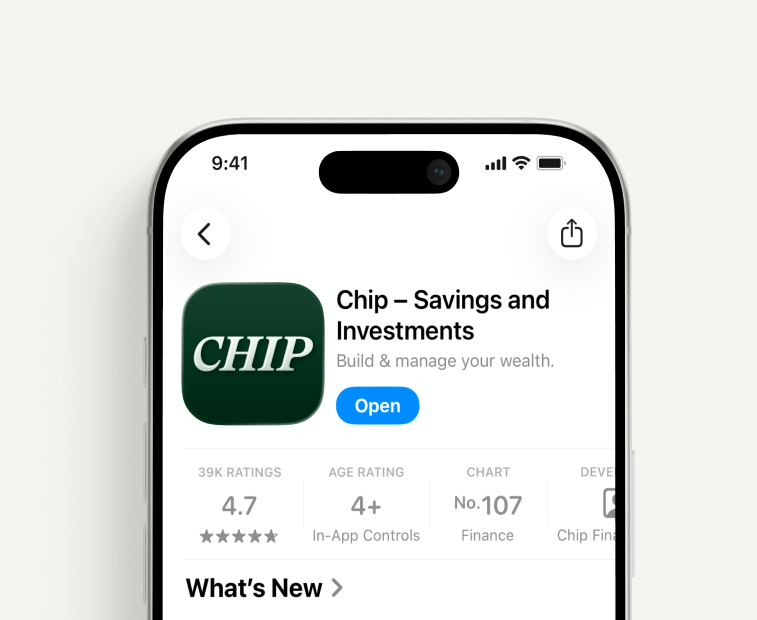
Download Chip
Get started by downloading the Chip app from the App Store or Google Play and sign up for an account.
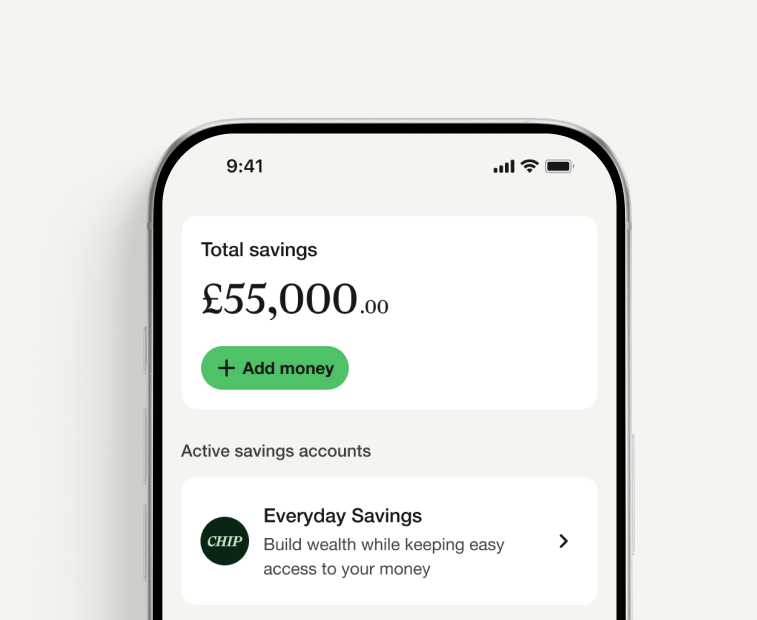
Open an Everyday Savings account
On the ‘Savings’ tab of your Chip app, select the Everyday Savings account
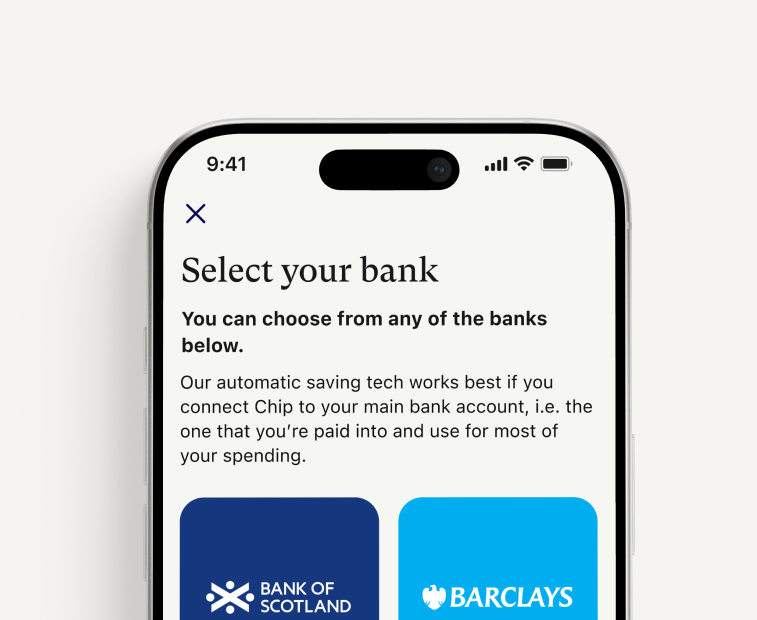
Connect your bank
In order to make instant saves and seamless withdrawals, you just need to connect your bank.
FSCS protected
Money deposited into the Everyday Saver is held across established UK licensed banks, such as HSBC Bank Plc, Lloyds, QNB and is eligible for cover by the Financial Services Compensation Scheme (FSCS), subject to FSCS conditions.
FSCS limits of £120,000 per person, per bank apply, subject to eligibility. As funds may be held across multiple UK licensed banks, protection applies separately to deposits held with each bank.
Protect yourself with biometrics
Protection for your mobile device with biometric login. As an additional security layer all Chip users need to create a 6-digit PIN to access their app.
Keeping your money safe
Bank-level encryption
Every connection to Chip is secured with bank-grade encryption and built on Open Banking technology – the regulated standard for seamlessly linking accounts.
Keeping your money safe
We’ve got your back
Our systems continuously monitor for suspicious activity, helping keep your account protected from fraudsters.
How we fight fraud
Help when you need it
Our UK-based customer support team is just a message away, ready to help whenever you need it.
Contact usSaving terms explained
Make sure you understand all the key saving terms when it comes to comparing and understanding how each of our savings accounts works.
AER (Annual Equivalent Rate)
The AER is the true rate of interest you'll earn on your savings over a year, taking into account how often the interest is paid and added to your balance (compounded).
It gives you a standardized way to compare different accounts, regardless of their specific interest payment schedule. A higher AER means your money will grow faster over the year.
Gross p.a (Gross per annum)
The Gross p.a rate is the headline interest rate paid on your savings before any income tax has been deducted from the earnings.
It represents the simple, stated rate of return on your money. The term 'per annum' (p.a.) confirms the rate is calculated annually, or over a period of one year.
FAQs
What is the Everyday Savings Account?
The Chip Everyday Savings Account is an easy-access savings account.
Chip deposits your money with one or more banks in trust accounts, which are kept separate from Chip's own money.
It's designed for money you want easy access to but don't need to hold in an ISA, alongside your other Chip savings.
Are there any fees for opening and holding an Everyday Savings Account?
There are no fees or charges for opening or holding an Everyday Savings Account.
Am I eligible to open an Everyday Savings Account?
To be eligible for an Everyday Savings Account, you must:
- Be over 18
- Be a UK resident (please notify us if at any point you cease to be a UK resident).
- Pay tax solely in the UK.
Can I hold more than one Everyday Savings Account?
You can only hold one Everyday Access Account at a time, as you can only open and hold one of each type of savings account on the Chip platform
How do I open an Everyday Savings Account?
We've made opening an Everyday Savings Account quick and easy!
Head to the Savings tab in your Chip app and select the option to open the account. We'll guide you through a couple of quick steps, which mainly involve accepting the terms and conditions.
What is the minimum and maximum I can deposit into my Everyday Savings Account?
The minimum amount you can deposit into your Everyday Savings Account is £1.
There is no maximum deposit amount for this account.
Can I allocate autosaves to my Everyday Savings Account?
No, this is because we can't accept debit card deposits for this account, and autosaves are processed from your linked debit card.
Can I allocate recurring deposits to my Everyday Savings Account?
No, it’s not possible to allocate recurring deposits to your Everyday Savings Account, but we’re working on this!
Can I close my Everyday Savings Account?
Yes. To close your Everyday Savings Account, contact our support team, and they can close it for you. Once your Everyday Savings Account is closed, you won't be able to reopen it.
Please note: You will receive your boost payout after 12 months. As long as your Everyday Savings Account is open, you will receive your boost payment. Any standard interest that hasn’t been paid out will be paid upon account closure.
What is the interest rate on the Everyday Savings Account?
How to check your rate
You can find your current interest rate at any time in the app. Just head to the Savings tab and select your Everyday Savings Account. This is also where you’ll see any boosted or loyalty rates you’re currently earning or are eligible for.
Looking for your rate history?
If you want to see a breakdown of the interest rates you’ve earned in the past, you can find this on your account statements. To download them, head to Profile.
What happens if I withdraw money from my Everyday Savings Account during the boost period?
Nothing happens to your boost. You can withdraw as much of your balance as you like, without losing any boost interest you've earned. Only closing the account forfeits unpaid boost interest; reducing your balance doesn't.
Is the Everyday Savings Account an ISA?
No. The Everyday Savings Account is a standard, non-ISA savings account. It doesn't use up any of your £20,000 ISA allowance, and interest earned isn't automatically tax-free, so it's worth checking this against your Personal Savings Allowance if you hold other savings outside an ISA.
Which banks hold my money in the Everyday Savings Account?
Chip deposits your money with one or more banks in trust accounts, segregated from Chip's own money. Your savings are currently placed across a panel of UK-regulated banks, anchored by HSBC Bank Plc, and this panel is subject to change. Chip does not offer any products that allow customers to make their own bank allocation selections. We exercise all due skill, care and diligence when selecting these banks.
What is a bare trust, and why does the Chip Everyday Savings Account use one?
A bare trust is a legal structure under which Chip Financial Group Ltd holds customer money on trust, while the customer remains the beneficial owner throughout. Chip Financial Wealth Ltd acts as deposit manager, placing funds across a panel of banks, currently anchored by HSBC Bank Plc. This structure allows Chip to place customer money across multiple banks rather than a single provider.
Bare Trust arrangements do not use Chip's payment services permission with the FCA but your funds are held with UK-regulated third-party banks under a bare trust agreement, meaning you benefit from FSCS protection and your funds are segregated from Chip's own money.
Why are withdrawals from the Everyday Savings Account not instant?
To secure a competitive rate on the Everyday Savings Account, Chip deposits your money with one or more banks in trust accounts, segregated from Chip's own money. Your savings are currently placed across a panel of UK-regulated banks, anchored by HSBC Bank Plc, and this panel is subject to change. Because we work with different institutions, we have to adhere to their varying timeframes. This means withdrawals cannot be instant and will land in your linked bank account by the end of the next working day.